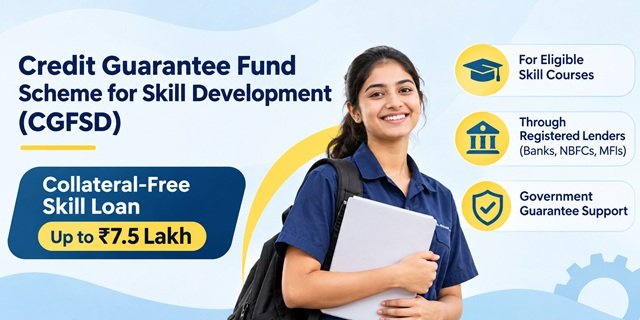
The Credit Guarantee Fund Scheme for Skill Development (CGFSD) is a Government of India initiative that supports collateral-free skill development loans of up to ₹7.5 lakh. Under the scheme, the National Credit Guarantee Trustee Company Limited (NCGTC) provides guarantee coverage to eligible banks and financial institutions against loan defaults. For loans up to ₹4 lakh, the scheme provides 75% guarantee coverage of the amount in default. Applicants must apply for a skill loan through an eligible lender, not directly to NCGTC.
Credit Guarantee Fund Scheme for Skill Development (CGFSD) Highlights | |
|---|---|
| Scheme Name | Credit Guarantee Fund Scheme for Skill Development (CGFSD), also known as CGFSSD or the Skill Loan Scheme |
| Type | Government credit guarantee scheme, not a direct loan or subsidy |
| Sponsored By | Ministry of Skill Development and Entrepreneurship (MSDE) |
| Managed By | National Credit Guarantee Trustee Company Limited (NCGTC), as the trustee of the fund |
| Launch Year | July 2015; the fund was notified on 20 November 2015 |
| Revised Scheme Launch | 25 July 2024, when the revised Model Skill Loan Scheme was launched |
| Objective | To improve access to affordable finance for skill development courses, particularly for youth from low-income families, and encourage lenders to provide loans without collateral security |
| Loan Amount | ₹5,000 to ₹7.5 lakh, without collateral security or a third-party guarantee; the earlier maximum limit was ₹1.5 lakh |
| Guarantee Coverage | 75% of the amount in default for loans up to ₹4 lakh, and 70% for loans above ₹4 lakh and up to ₹7.5 lakh |
| Guarantee Fee | 0.125% per quarter (0.50% per year) on the eligible outstanding loan portfolio at the end of each quarter, payable by the lender |
| Maximum Interest Rate | Up to 1.5% above the External Benchmark Lending Rate (EBLR) for banks and up to 21% per annum for NBFCs and microfinance institutions |
| Processing Fee | No processing fee can be charged to the trainee |
| Margin Money | No fixed margin is prescribed under the scheme; the lending institution decides the applicable requirement |
| Repayment Period | Up to 3 years for loans up to ₹50,000, up to 5 years for loans above ₹50,000 and up to ₹1 lakh, and up to 7 years for loans above ₹1 lakh |
| Moratorium Period | Up to 6 months after completion of a course lasting up to one year, and up to 12 months after completion of a course lasting more than one year |
| Eligible Courses | NSQF-aligned courses and eligible non-NSQF courses offered by training entities onboarded on the Skill India Digital Hub (SIDH); no minimum course duration is prescribed |
| Eligible Institutes | Eligible ITIs, polytechnics, recognised schools and affiliated colleges, along with qualifying training partners of NSDC, Sector Skill Councils and State Skill Missions |
| Eligible Borrowers | New or existing borrowers of Indian nationality who secure admission to an eligible skill course; a parent or guardian must join as the co-borrower |
| Ineligible Loans | Loans exceeding ₹7.5 lakh, loans secured by collateral under the scheme, loans carrying interest above the prescribed ceiling, and loans covered by another guarantee or insurance arrangement |
| Eligible Lenders | Public sector banks, private sector banks, foreign banks, small finance banks, NBFCs and NBFC-MFIs registered with NCGTC under the scheme |
| Guarantee Claim Rules | Lock-in period of 6 months for loans up to ₹3 lakh and 12 months for loans above ₹3 lakh; the lender must submit the claim within the prescribed period after the account becomes a non-performing asset (NPA) |
| Annual Payout Limit | 20% of the eligible loan portfolio for FY 2024-25 and FY 2025-26, and 15% from FY 2026-27, as specified in the applicable scheme provisions |
| How to Apply | Apply for a skill loan at an eligible bank or registered lending institution with the required documents of the trainee and co-borrower |
| Direct Application to NCGTC | Not required. The lending institution applies for guarantee coverage and pays the applicable guarantee fee within the prescribed period |
| NCGTC Office Address | 1410, 14th Floor, Parinee Crescenzo, Bandra Kurla Complex, Mumbai – 400051 |
| Helpdesk Details | Email: cgfsd@ncgtc.in; Phone: 022-69035615; Board Number: 022-69035600 |
| Official Websites | NCGTC CGFSD Official Scheme Page |
Introduction of Credit Guarantee Fund Scheme for Skill Development (CGFSD): A Brief Insight
A young person may secure admission to a good skill development course in fields such as data science, hospitality or drone technology, but the high course fee can become a major financial challenge for the family. Many students also struggle to get a loan because they cannot provide property or other assets as security.
To address this problem, the Government of India introduced the Credit Guarantee Fund Scheme for Skill Development (CGFSD). Under this scheme, the Government provides credit guarantee support to lenders, allowing banks and finance companies to offer skill development loans without asking for collateral security or a third-party guarantee.
The scheme is also known as the Skill Loan Scheme. The Ministry of Skill Development and Entrepreneurship (MSDE) launched it in July 2015, and the Government notified the fund on 20 November 2015. Later, on 25 July 2024, the Ministry introduced the revised Model Skill Loan Scheme to expand access to financial support for skill training.
The National Credit Guarantee Trustee Company Limited (NCGTC) manages the fund as its trustee. NCGTC is a Government of India company responsible for managing credit guarantee funds under various government schemes.
The main objective of CGFSD is to help young people, especially those from low-income families, access affordable loans for skill development and advanced training courses. It also encourages banks and financial institutions to provide loans for skill training without demanding collateral security.
Under the revised Skill Loan Scheme, eligible trainees can get a loan of up to ₹7.5 lakh, compared with the earlier limit of ₹1.5 lakh. The minimum loan amount starts at ₹5,000. The credit guarantee covers 75% of the amount in default for loans up to ₹4 lakh and 70% for loans above ₹4 lakh and up to ₹7.5 lakh, as specified in the scheme guidelines.
The lending institution pays the guarantee fee to NCGTC from its own funds. It cannot recover this fee from the trainee or charge a processing fee for a loan sanctioned under the scheme.
Eligible lending institutions include public sector banks, private sector banks, foreign banks, small finance banks, non-banking financial companies (NBFCs) and microfinance institutions. However, these institutions must register with NCGTC to provide loans under the scheme.
The scheme covers eligible courses aligned with the National Skill Qualification Framework (NSQF) and other qualifying courses listed on the Skill India Digital Hub (SIDH). Both new and existing borrowers of Indian nationality can apply. A parent or guardian must join the applicant as a co-borrower.
Borrowers can get a moratorium of up to 6 months after completing a course of up to one year and up to 12 months for a course lasting more than one year. The repayment period can extend up to 7 years, depending on the loan amount.
One important point to remember is that trainees do not need to apply directly to NCGTC. They must approach a bank or another eligible lending institution for a skill loan. The lender then completes the required formalities to obtain credit guarantee coverage from NCGTC.
For assistance, applicants can contact their bank’s loan officer or write to the NCGTC helpdesk in Mumbai. The official contact address, email ID and telephone numbers are provided in the contact section below.
Young people who want to receive skill training without paying course fees can also explore the Pradhan Mantri Kaushal Vikas Yojana (PMKVY). Rural youth can check the Deen Dayal Upadhyaya Grameen Kaushalya Yojana (DDU-GKY) for skill training and employment opportunities.
Students seeking financial assistance for higher education at leading institutions can read about the PM Vidyalaxmi Scheme. Those planning to pursue a degree and looking for education loan support can also explore the Credit Guarantee Fund Scheme for Education Loans.
Young people, trainees, parents, job seekers and other readers looking for skill development, education and financial assistance programmes can explore more schemes on our Central Government List of Welfare Schemes page.
Benefits Provided to Eligible Beneficiaries
The Credit Guarantee Fund Scheme for Skill Development (CGFSD) helps young Indians pursue vocational and advanced skill development courses without arranging property or other collateral security for a skill loan. Under this scheme, the Government of India provides credit guarantee support to participating lending institutions, encouraging them to offer collateral-free loans to eligible trainees. The revised Model Skill Loan Scheme, launched on 25 July 2024, increased the maximum loan amount from ₹1.5 lakh to ₹7.5 lakh and expanded the number of eligible lending institutions. Here are the major benefits available under the scheme.
Major Benefits Available to Trainees
- Loan up to ₹7.5 Lakh: Eligible trainees can obtain a skill loan ranging from ₹5,000 to ₹7.5 lakh, depending on their course fees and eligible training expenses.
- No Collateral Security: Applicants do not need to mortgage their house, land or other property to obtain a loan covered under the scheme.
- No Third-Party Guarantee: The lending institution cannot demand a third-party guarantor for a loan covered under the credit guarantee facility. However, a parent or guardian acts as a co-borrower.
- No Processing Fee: Participating banks cannot charge a processing fee on skill loans covered under the scheme.
- Coverage of Course Expenses: The loan can cover tuition fees, examination fees, assessment charges, library and laboratory expenses, books, tools, equipment and other eligible course-related expenses.
- Boarding and Lodging Expenses: Applicants may also receive loan assistance for boarding and lodging when they need accommodation away from home to attend their training course, subject to the lender’s assessment.
- Support for Advanced Skill Courses: The revised scheme encourages access to advanced and industry-relevant courses in sectors such as healthcare, artificial intelligence, data science, information technology, cloud computing, hospitality, digital marketing and drone technology.
- Short-Term Course Coverage: The scheme does not prescribe a minimum course duration, allowing eligible trainees to seek financial assistance for short-term skill development programmes as well.
- Wider Access to Lending Institutions: Applicants can approach eligible scheduled banks, Small Finance Banks, NBFCs and NBFC-MFIs that participate in the scheme.
Credit Guarantee Support Provided to Lending Institutions
One of the major features of CGFSD is that it protects participating lending institutions against a specified portion of the loan default. The National Credit Guarantee Trustee Company Limited (NCGTC) administers this guarantee facility on behalf of the Government of India.
- Government-Backed Credit Guarantee: The fund provides guarantee coverage against eligible loan defaults, reducing the financial risk for participating lenders.
- Higher Guarantee Coverage: The Ministry of Skill Development and Entrepreneurship’s Year-End Review 2025 reports that guarantee coverage for lower-ticket loans increased from 75% to 85% under the revised scheme.
- Expanded Lending Network: The scheme now includes NBFCs, NBFC-MFIs and Small Finance Banks in addition to eligible scheduled banks.
- Reduced Lock-In Period: The revised scheme reduced the lock-in period for invoking the guarantee from 12 months to 6 months.
- Portfolio-Based Guarantee: Participating lenders can obtain guarantee coverage for eligible skill loans through a portfolio-based arrangement rather than submitting a separate guarantee application for every individual loan.
Loan Repayment Period and Moratorium
The Skill Loan Scheme provides a structured repayment facility so that trainees can manage their loan obligations after completing their training. The applicable repayment period and moratorium depend on the loan amount, course duration and terms prescribed by the lending institution.
Under the existing Model Skill Loan framework, the repayment tenure can extend up to 7 years, depending on the amount borrowed. Applicants should check the repayment schedule and the applicable moratorium period in their bank’s loan sanction letter before accepting the loan.
Difference Between the Earlier and Revised Skill Loan Scheme
The Government revised the Model Skill Loan Scheme in July 2024 to increase access to institutional credit and support higher-value skill development courses. The major changes include:
| Particulars | Earlier Provision | Revised Provision |
|---|---|---|
| Maximum Loan Amount | ₹1.5 lakh | ₹7.5 lakh |
| Eligible Lending Institutions | Eligible banks | Scheduled Banks, Small Finance Banks, NBFCs and NBFC-MFIs |
| Course Eligibility | Mainly NSQF-aligned courses | NSQF-aligned courses and eligible non-NSQF courses available through the Skill India Digital Hub |
| Guarantee Coverage | 75% under the earlier provisions | Enhanced coverage for lower-ticket loans, reported at 85% in the Ministry’s Year-End Review 2025 |
| Lock-In Period for Guarantee Claims | 12 months | 6 months |
Important Things Beneficiaries Should Know
- Loan Repayment Is Mandatory: The credit guarantee protects the lending institution against a specified portion of its loss. It does not waive the borrower’s responsibility to repay the loan.
- Loan Approval Is Not Automatic: Meeting the scheme conditions does not guarantee loan approval. The lending institution assesses the applicant’s course, documents and loan proposal before sanctioning the amount.
- Interest Must Be Repaid: The loan is not an interest-free financial assistance programme. Applicants must repay the principal amount along with the applicable interest.
- Guarantee Fee Is Not the Borrower’s Expense: The participating lending institution pays the applicable guarantee fee to NCGTC. It should not transfer this fee to the trainee.
- No Direct Financial Assistance: NCGTC does not transfer the loan amount to the trainee. The participating bank or financial institution provides the loan and generally pays the eligible course fee directly to the training institute.
- Collateral-Free Does Not Mean Loan Waiver: If the borrower defaults, the lending institution can continue recovery proceedings against the borrower and co-borrower even after receiving a guarantee claim from NCGTC.
Eligibility Conditions Required to be Fulfilled
The Credit Guarantee Fund Scheme for Skill Development (CGFSD) supports skill loans provided by eligible banks and financial institutions to candidates who want to pursue vocational or skill-based training courses. Indian nationals can avail of this facility if they meet the course admission requirements and fulfil the conditions of the Skill Loan Scheme. Applicants must check the following eligibility conditions before approaching a lending institution.
Basic Eligibility Conditions for Applicants
- The applicant must be an Indian national.
- The applicant must have secured admission or a confirmed seat in an eligible skill development or vocational training course.
- The applicant must meet the minimum educational qualification and admission requirements prescribed for the selected course.
- A parent or guardian must act as a co-borrower along with the trainee.
- Both new and existing borrowers can apply, subject to the lender’s loan assessment and applicable scheme conditions.
- The scheme does not prescribe a specific minimum or maximum age limit. However, applicants must fulfil the admission requirements of their chosen course and the lender’s applicable conditions.
- The scheme does not prescribe a uniform income ceiling for applicants. However, the lending institution may assess the financial details of the applicant and co-borrower before sanctioning the loan.
Eligible Loan Amount and Loan Conditions
- The applicant can seek a skill loan ranging from ₹5,000 to ₹7.5 lakh, depending on the course fee and eligible expenses.
- The loan must be sanctioned without any collateral security or third-party guarantee.
- A parent or guardian can act as a co-borrower. This requirement is different from a third-party guarantee.
- The loan must cover eligible expenses related to the selected skill development course.
- The lending institution must sanction the loan under the applicable Skill Loan Scheme guidelines and obtain credit guarantee coverage through NCGTC.
- The bank or financial institution cannot charge a processing fee for a loan covered under the scheme.
- The scheme does not prescribe a fixed margin requirement. The lending institution may decide the applicable margin as per its lending policy.
Eligible Courses and Training Institutes
The applicant must enrol in a course that meets the eligibility requirements of the revised Model Skill Loan Scheme. The following courses and training institutions qualify under the scheme:
- NSQF-Aligned Courses: Courses aligned with the National Skill Qualification Framework (NSQF) qualify for skill loan assistance. The scheme does not prescribe any minimum course duration.
- Skill India Digital Hub Courses: Non-NSQF-aligned courses offered by training entities onboarded on the Skill India Digital Hub (SIDH) also qualify, subject to the applicable scheme conditions.
- Industrial Training Institutes (ITIs): Applicants enrolled in eligible vocational and technical courses offered by recognised ITIs can apply.
- Polytechnic Institutes: Students pursuing eligible courses from polytechnic institutions can avail of the loan.
- Recognised Schools: Courses offered by schools recognised by Central or State Education Boards qualify, subject to the scheme requirements.
- Recognised Colleges: Applicants pursuing eligible courses from colleges affiliated with recognised universities can apply.
- NSDC and Other Training Partners: Courses offered by training partners affiliated with the National Skill Development Corporation (NSDC), Sector Skill Councils, State Skill Missions and State Skill Corporations are also covered, subject to the applicable eligibility conditions.
The revised Model Skill Loan Scheme also aims to support advanced and industry-oriented skill courses. These include training programmes in healthcare, information technology, data science, cloud applications, digital marketing, hospitality, animation, gaming, graphic design and drone technology.
Interest Rate Conditions
The lending institution must follow the interest rate limits prescribed under the revised scheme while providing a guaranteed skill loan.
- Scheduled Banks: The interest rate must not exceed 1.5% per annum above the External Benchmark Lending Rate (EBLR).
- NBFCs and NBFC-MFIs: The interest rate must not exceed 21% per annum.
Applicants should confirm the applicable interest rate, repayment period and other loan terms with their selected lending institution before accepting the loan offer.
Eligible Banks and Financial Institutions
Applicants must approach a bank or financial institution that participates in the Credit Guarantee Fund Scheme for Skill Development. The eligible lending institutions include:
- Scheduled Commercial Banks.
- Small Finance Banks.
- Non-Banking Financial Companies (NBFCs).
- NBFCs operating as Microfinance Institutions (NBFC-MFIs).
The lending institution must register with the National Credit Guarantee Trustee Company Limited (NCGTC) to avail of the guarantee facility. Applicants should confirm whether their chosen lender offers skill loans under this scheme before submitting an application.
Who Cannot Avail of the Scheme?
An applicant or loan may not qualify for guarantee coverage under the scheme in the following circumstances:
- The applicant is not an Indian national.
- The selected course does not meet the applicable NSQF or Skill India Digital Hub eligibility requirements.
- The training institute does not fall under the recognised or eligible categories prescribed by the scheme.
- The requested loan amount is below ₹5,000 or exceeds the maximum limit of ₹7.5 lakh.
- The loan requires collateral security or a third-party guarantee as a condition for guarantee coverage.
- The loan carries an interest rate above the prescribed ceiling for the respective lending institution.
- The loan already receives overlapping guarantee coverage from another government-backed fund or guarantee scheme, to the extent prohibited under the applicable guidelines.
- The lending institution is not registered with NCGTC or does not participate in the scheme.
Important Points to Check Before Applying
- Confirm that your selected course and training institute meet the scheme’s eligibility conditions.
- Check that your required loan amount falls between ₹5,000 and ₹7.5 lakh.
- Arrange a parent or guardian as a co-borrower before approaching the lender.
- Confirm the interest rate, repayment period and applicable loan conditions with the bank or financial institution.
- Ensure that the lender offers skill loans under the CGFSD scheme and can obtain the required guarantee coverage from NCGTC.
- Remember that the credit guarantee protects the lending institution against a specified portion of the loan default. It does not waive the borrower’s responsibility to repay the loan.
- Do not pay any agent or intermediary to obtain a skill loan or credit guarantee under the scheme.
Documents Required to be Attached
Applicants must keep the following documents ready while applying for a Skill Loan under the Credit Guarantee Fund Scheme for Skill Development (CGFSD). The lending bank or financial institution may ask for these documents to verify the applicant’s identity, admission details, course fees and repayment capacity.
Identity and Address Proof
- Aadhaar Card of the applicant.
- PAN Card, Voter ID Card or Driving Licence as identity proof, as required by the lending institution.
- Address Proof, such as a Voter ID Card, Passport or recent Utility Bill, if required separately.
- Recent Passport-Size Photographs of the applicant.
Course and Admission Documents
- Admission Letter or Offer Letter issued by the eligible training institute.
- Course Details mentioning the name, duration and other relevant information about the training programme.
- Proof of Recognition or Eligibility of the Training Institute, wherever required.
- Educational Certificates and Mark Sheets showing that the applicant meets the minimum qualification required for the course.
Course Fee and Expense Documents
- Official Fee Structure issued by the training institute, mentioning the tuition fee and other applicable charges.
- Details of additional course-related expenses, such as examination fees, assessment fees, library charges, laboratory charges, books, tools and equipment, if these expenses are included in the loan requirement.
- Boarding and Lodging Expense Details, if the applicant needs accommodation away from home during the training period.
Bank Account Details
- Bank Passbook or Cancelled Cheque showing the applicant’s bank account details.
- Recent Bank Statements, if requested by the lending institution.
Documents of the Co-Borrower
A parent or guardian acts as the co-borrower under the Skill Loan Scheme. The following documents may be required from the co-borrower:
- Aadhaar Card and PAN Card.
- Address Proof.
- Income Proof, such as Salary Slips or an Income Certificate, if required by the bank.
- Recent Bank Statements, as requested by the lending institution.
- Proof of Relationship with the applicant, wherever required.
How Beneficiaries Can Apply to Avail the Benefit of this Scheme
You cannot apply directly to the National Credit Guarantee Trustee Company Limited (NCGTC) to get the benefit of the Credit Guarantee Fund Scheme for Skill Development (CGFSD). Instead, you must apply for a skill loan through a participating bank or financial institution. The lender then approaches NCGTC to get a guarantee for your loan. This guarantee gives the lender confidence to provide loans without asking you to mortgage your house, land or other property. In simple words, the Government supports the lender if a borrower fails to repay the loan, but you must repay the loan according to the agreed terms. You only need to choose an eligible course, arrange the required documents and approach a participating lender. Follow the steps below to understand the complete application process. If you want free skill training instead of taking a loan, you can also read our guide to the Pradhan Mantri Kaushal Vikas Yojana.
Before You Start
Step 1: First, choose the skill development course you want to pursue. Contact the training institute and get your admission letter or offer letter. This letter will show that you have secured admission or a seat in the course.
Step 2: Check whether your selected course is eligible under the scheme. Generally, the course must be aligned with the National Skill Qualification Framework (NSQF) or be available through an eligible training entity on the Skill India Digital Hub. Visit the Skill India Digital Hub and check the official CGFSD page on the NCGTC website for scheme-related information.
Step 3: Ask your training institute for the official course fee structure. Also, find out how long the course will take to complete. Keep these details ready because the bank will need them to decide your loan amount.
Step 4: Calculate how much money you need for the course. You can apply for a skill loan between ₹5,000 and ₹7.5 lakh, subject to the eligible expenses and the lender’s assessment. You must also arrange a parent or guardian who can join you as a co-borrower.
Step 5: Collect your documents and the documents of your co-borrower. Keep your Aadhaar Card, PAN Card, educational certificates, admission letter, course fee details and bank account information ready. Your co-borrower may also need to provide identity proof, address proof and other documents required by the lender. You can check the complete list in the Documents Required section above.
Method 1: Go to a Bank Branch
Step 1: Visit a nearby public sector bank, private sector bank, foreign bank or Small Finance Bank. Before visiting, check whether the bank provides skill loans under the Credit Guarantee Fund Scheme for Skill Development.
Step 2: Meet the bank’s loan officer and explain that you want a skill loan to pay for your training course. Tell the officer that you want the loan under the CGFSD credit guarantee facility.
Step 3: Ask the bank for the skill loan application form. Fill in your personal details, course information, required loan amount and co-borrower’s details carefully. Your parent or guardian must also provide the required information and sign wherever necessary.
Step 4: Attach the required documents with the application form and submit them to the bank. Ask for an acknowledgement or application reference number so that you can check your application status later.
Step 5: Ask the loan officer whether the bank will cover your loan under CGFSD. Also, confirm that the bank will provide the loan without collateral security or a third-party guarantee, as required under the scheme.
Step 6: Ask the bank about the applicable interest rate, repayment period and moratorium. Get these details in writing before accepting the loan. For scheduled banks, the interest rate must follow the applicable ceiling under the scheme, which is linked to the External Benchmark Lending Rate (EBLR).
Step 7: Confirm that the bank will not charge any processing fee for the loan covered under the scheme. If the bank asks for any additional charges, request a clear explanation before paying anything.
Method 2: Go to a Finance Company or a Microfinance Institution
Step 1: You can also approach an eligible Non-Banking Financial Company (NBFC) or NBFC-MFI that provides skill loans. Contact its branch or customer support to find out whether it offers loans under the CGFSD scheme.
Step 2: Ask the company whether it is registered with NCGTC for this scheme. Registration is important because an NBFC cannot use the CGFSD guarantee facility unless it meets the scheme’s requirements.
Step 3: If the company offers the required loan facility, collect its application form. Fill it in with your details, attach the necessary documents and submit it along with your co-borrower’s documents. Keep the application acknowledgement for future reference.
Step 4: Ask the company to provide its interest rate in writing. Under the revised scheme, the applicable interest rate for NBFCs and NBFC-MFIs must not exceed 21% per annum.
Step 5: Before accepting the loan, compare the interest rate and repayment conditions with those offered by banks. Choose the lender that provides suitable loan terms and clearly confirms that your loan will receive CGFSD guarantee coverage.
Method 3: Ask Your Training Institute
Step 1: Visit the admission office or contact the help desk of your training institute. Tell them that you need a skill loan to pay the course fee under the Credit Guarantee Fund Scheme for Skill Development.
Step 2: Ask the institute whether any bank or financial institution already provides skill loans to its students. Many training institutes can guide students towards lenders that finance their courses.
Step 3: Contact the suggested banks or financial institutions and confirm whether they provide loans under CGFSD. Also, check whether they are eligible to obtain the guarantee from NCGTC.
Step 4: Once the bank approves your loan, it generally pays the eligible course fee directly to the training institute. This means you do not have to receive the entire loan amount in your personal bank account and then pay the institute yourself.
If the Trainee Is a Minor
If the applicant is below 18 years of age, a parent or guardian must complete the required loan formalities as the co-borrower. The following steps explain the process:
Step 1: The parent or guardian must approach the lending institution and sign the required loan documents as the co-borrower.
Step 2: Inform the bank that the trainee is below 18 years of age. Submit the minor’s documents and complete the additional formalities required by the lender.
Step 3: After the trainee becomes an adult, he or she must provide the required letter of acceptance to the lender, as prescribed under the scheme.
What Happens at the Lender
After you submit your application, the bank or financial institution checks your details and decides whether to approve the loan. The following steps explain what happens after submission:
Step 1: The lender checks your identity, admission letter, course details, fee structure and other submitted documents. It also examines the details of your parent or guardian acting as the co-borrower.
Step 2: The lender checks whether your course and training institute meet the scheme’s eligibility conditions. It also assesses the loan amount and your repayment-related details.
Step 3: If everything is satisfactory, the lender decides whether to approve your loan. If it sanctions the loan under CGFSD, it can provide the eligible amount without asking you to mortgage property or arrange a third-party guarantor.
Step 4: Before signing the loan agreement, carefully read the interest rate, repayment schedule, moratorium period and other conditions. Ask the bank to explain anything you do not understand. Keep a copy of the signed loan agreement and other important documents.
Step 5: After completing the required formalities, the lender disburses the loan according to the approved terms. The eligible course fee is generally paid directly to the training institute.
What the Lender Does With NCGTC
You do not need to complete this process yourself. The bank or financial institution handles all guarantee-related formalities with NCGTC. However, understanding this process will help you know how your loan receives government-backed credit guarantee support.
Step 1: First, the lending institution must register with NCGTC and complete the required agreement formalities. Only eligible registered lenders can use the guarantee facility.
Step 2: The lender groups its eligible skill loans into a portfolio. In simple words, it prepares a combined record of the loans covered under the scheme instead of submitting a separate guarantee application for every borrower.
Step 3: The lender submits the required portfolio details and management certificate to NCGTC within the prescribed timeline. This confirms that the loans meet the applicable scheme conditions.
Step 4: NCGTC calculates the applicable guarantee fee and issues the demand note. The lender pays this fee from its own funds within the prescribed period. The borrower does not have to pay this guarantee fee.
Step 5: The lender completes the required reporting, fee payment and renewal formalities to keep the guarantee coverage active according to the scheme guidelines.
After You Get the Loan
Getting a skill loan is only the first step. You must also complete your training and repay the borrowed amount according to the loan agreement. Follow these steps after receiving the loan:
Step 1: Attend your training classes regularly and complete the course. Use the loan amount only for the expenses approved by the lending institution.
Step 2: Check the moratorium period mentioned in your loan agreement. Under the Model Skill Loan Scheme, the applicable moratorium can extend up to 6 months after a course of up to one year and up to 12 months after a course lasting more than one year.
Step 3: Start repaying your loan according to the repayment schedule. Remember that the credit guarantee does not make your loan free or cancel your repayment responsibility.
Step 4: If you have enough money, ask your lender about early repayment or foreclosure conditions. Check the applicable rules before making an early payment.
Step 5: If you face financial difficulties or cannot pay an instalment on time, contact your lender immediately. Discuss the available options instead of ignoring repayment notices or allowing the account to become overdue.
If the Lender Says No
Your loan application may not receive approval even if you meet the basic eligibility conditions. The bank can reject an application after checking the course, documents and other loan-related details. If this happens, follow these steps:
Step 1: Ask the bank or financial institution to explain why it rejected your application. Request the reason in writing so that you understand what went wrong.
Step 2: If the problem relates to missing documents or incorrect information, correct it and submit the required documents again. If your course is not eligible, check whether another eligible course is available.
Step 3: You can approach another participating bank or financial institution and ask whether it offers skill loans under CGFSD. Different lenders may follow different loan assessment policies.
Step 4: If you want to explore other government support for skill development, visit the official information published by the Ministry of Skill Development and Entrepreneurship.
Important Links Available of the Scheme
- CGFSD Official Guidelines, Skill Loan Eligibility, Guarantee Coverage and Eligible Courses
- Revised Model Skill Loan Scheme: Loans up to ₹7.5 Lakh
- Skill Loan Scheme and Skill India Digital Hub
- Skill India Digital Hub Search Eligible Skill Development Courses
- National Credit Guarantee Trustee Company (NCGTC) Official Website
- NCGTC Contact Details and Grievance Support
Contact Details in Case of Help Needed
- Office: National Credit Guarantee Trustee Company Limited (NCGTC), 1410, 14th Floor, Parinee Crescenzo, Plot No. C-38 and C-39, G-Block, Bandra Kurla Complex, Bandra East, Mumbai, Maharashtra – 400051
- CGFSD Helpdesk Email: cgfsd@ncgtc.in
- CGFSD Helpdesk Phone: 022-69035615 and 022-69035607
- Board Number: 022-69035600
- General Email: info@ncgtc.in
- Grievance Email: grievance@ncgtc.in
- Your Lender: The loan officer of the bank, finance company or microfinance institution where you apply, who decides on your loan and who asks NCGTC for the guarantee
Frequently Asked Questions (FAQs)
Ans. The Credit Guarantee Fund Scheme for Skill Development (CGFSD) is a Government of India initiative that supports skill-based education and training through collateral-free loans. Under this scheme, eligible lenders can provide skill loans of ₹5,000 to ₹7.5 lakh without requiring collateral security or a third-party guarantee. NCGTC provides credit guarantee support to lenders against eligible loan defaults.
Ans. The Ministry of Skill Development and Entrepreneurship (MSDE) sponsors the scheme, while the National Credit Guarantee Trustee Company Limited (NCGTC) manages the guarantee fund as its trustee. You can read the official CGFSD guidelines on the NCGTC website.
Ans. The Government introduced the Credit Guarantee Fund Scheme for Skill Development in July 2015. On 25 July 2024, the Ministry launched the revised Model Skill Loan Scheme. It increased the maximum loan amount eligible for guarantee cover from ₹1.5 lakh to ₹7.5 lakh and allowed NBFCs, microfinance institutions and small finance banks to provide eligible skill loans. Read the official PIB announcement.
Ans. Eligible borrowers can receive a skill loan ranging from ₹5,000 to ₹7.5 lakh. The lender sanctions the loan after checking the applicant’s eligibility, course details and other lending requirements.
Ans. The guarantee coverage depends on the loan category and applicable scheme guidelines. According to the Ministry’s update published in January 2026, the guarantee coverage for lower-ticket loans increased from 75% to 85%. Borrowers should check the latest NCGTC guidelines for the exact coverage applicable to their loan amount. This guarantee protects the lender against eligible defaults; it does not waive the borrower’s repayment responsibility.
Ans. No. A trainee must apply for a skill loan through an eligible bank, NBFC or other registered lending institution. The lender handles the credit guarantee process with NCGTC. Trainees do not need to submit a separate guarantee application to NCGTC.
Ans. The lending institution pays the guarantee fee to NCGTC for obtaining coverage under the scheme. The NCGTC FAQ specifies a standard fee of 0.125% per quarter (0.50% per year) on the eligible outstanding loan portfolio. Lending institutions cannot charge a processing fee on skill loans sanctioned under this scheme.
Ans. A new or existing borrower of Indian nationality can apply if they meet the course and other eligibility conditions. The applicant must secure admission to an eligible skill development course and complete the loan formalities with an eligible lender. A parent or guardian must act as the co-borrower. The official NCGTC FAQ does not specify a separate fixed age or income limit, but lenders may apply their own assessment requirements.
Ans. The scheme covers NSQF-aligned skill courses and eligible non-NSQF courses offered by training entities onboarded on the Skill India Digital Hub (SIDH). The eligible course lists are updated from time to time. Applicants can check the Skill India Digital Hub and the NCGTC scheme page before applying.
Ans. Eligible lending institutions include scheduled public sector banks, private sector banks, foreign banks, small finance banks, NBFCs and NBFC-MFIs registered with NCGTC under the scheme. Applicants should confirm that their chosen lender appears on the official list of registered lending institutions.
Ans. According to the NCGTC FAQ, scheduled banks cannot charge more than 1.5% per annum above the External Benchmark Lending Rate (EBLR). NBFCs and NBFC-MFIs cannot charge more than 21% per annum. Applicants should ask the lender to provide the applicable interest rate and repayment terms in writing.
Ans. The repayment period depends on the sanctioned loan amount. The NCGTC FAQ specifies the following maximum repayment periods:
– Loan up to ₹50,000: Up to 3 years.
– Loan above ₹50,000 and up to ₹1 lakh: Up to 5 years.
– Loan above ₹1 lakh: Up to 7 years.
Ans. The borrower gets a moratorium period after completing the course. Under the NCGTC FAQ, the applicable period is up to 6 months for courses lasting up to one year and up to 12 months for courses lasting more than one year. The lender decides the final repayment schedule according to the scheme guidelines and loan agreement.
Ans. No. Eligible skill loans covered under CGFSD do not require collateral security or a third-party guarantee. However, a parent or guardian must act as the co-borrower, as required under the scheme.
Ans. The scheme does not prescribe a fixed margin money requirement. The lending institution can decide whether to require margin money while processing the loan application. Applicants should confirm this condition with their lender before applying.
Ans. Contact your bank or lending institution first for loan-related queries. For questions about the credit guarantee scheme, you can contact NCGTC through its official email address, cgfsd@ncgtc.in, or telephone number, 022-69035615. You can also visit the official NCGTC contact page. Avoid paying agents or middlemen for loan approval.
Tabassum is a government schemes researcher and writer with 5 years of experience tracking Central and State welfare scheme programmes across India. She has covered 500+ schemes spanning agriculture, women welfare, education, and housing, helping lakhs of beneficiaries understand their entitlements in simple language.